China’s 2025 green packaging regime accelerates the phase-down of non-recyclable and non-compostable single-use plastics, tightens over-packaging limits, expands EPR pilots, and mandates clearer labeling and traceability across e-commerce, foodservice, and FMCG. Winning strategies: paperization and molded fiber (bagasse), PFAS-free aqueous or PLA barrier systems, mono-material thinking, right-sizing for logistics, and province-aware rollouts. Use a 12-month roadmap—audit, redesign, certify, pilot in high-enforcement cities, scale nationwide, and embed EPR data—to de-risk compliance and protect margins.
Regulatory Context & Strategic Takeaways
What is changing in 2025? Stricter controls on non-degradable single-use plastics; mandatory recyclable/compostable options in express logistics and takeaway; tighter rules on excessive layers/voids; clearer material labeling and end-of-life disclosures; broader EPR pilots with digital reporting.
Why it matters now: 2025 is an enforcement inflection point. Non-compliance risks lost channels, platform penalties, and reputational damage. Aligning China specs with EU/US expectations also unlocks export growth.
How to comply fast: 1) Portfolio audit → 2) Redesign to mono-material paper/bagasse/PLA → 3) Food-contact & compostability tests → 4) Pilot in Hainan/Shanghai-like hubs → 5) Switch logistics consumables (paper mailers/tapes, right-sizing) → 6) Scale with EPR data and QR traceability.
Options that work: Bagasse bowls/trays; kraft bowls with paper/PP lids; PLA/CPLA cold cups; PFAS-free aqueous coatings; barrier papers; reusable totes for intra-city loops; “cutlery on request”.
Considerations & risk controls: Avoid mixed laminates unless separable; document every claim (standard #, test report); second-source critical SKUs; province-aware BOMs; track KPIs: % recyclable/compostable SKUs, layers/order, leakage/warp rate, take-back weight, audit pass rate.
1) Context: Why 2025 is a Turning Point
China is the world’s largest packaging producer and one of the most dynamic consumer markets. Since the national single-use plastic control roadmap (2019–2025), policy has tightened in waves: phasing out certain plastic bags and utensils, curbing over-packaging, and pushing recycling and compostability in express logistics and foodservice. In 2025, several commitments mature, creating a compliance inflection point:
Retailers and platforms face stricter limits on non-recyclable and non-degradable items.
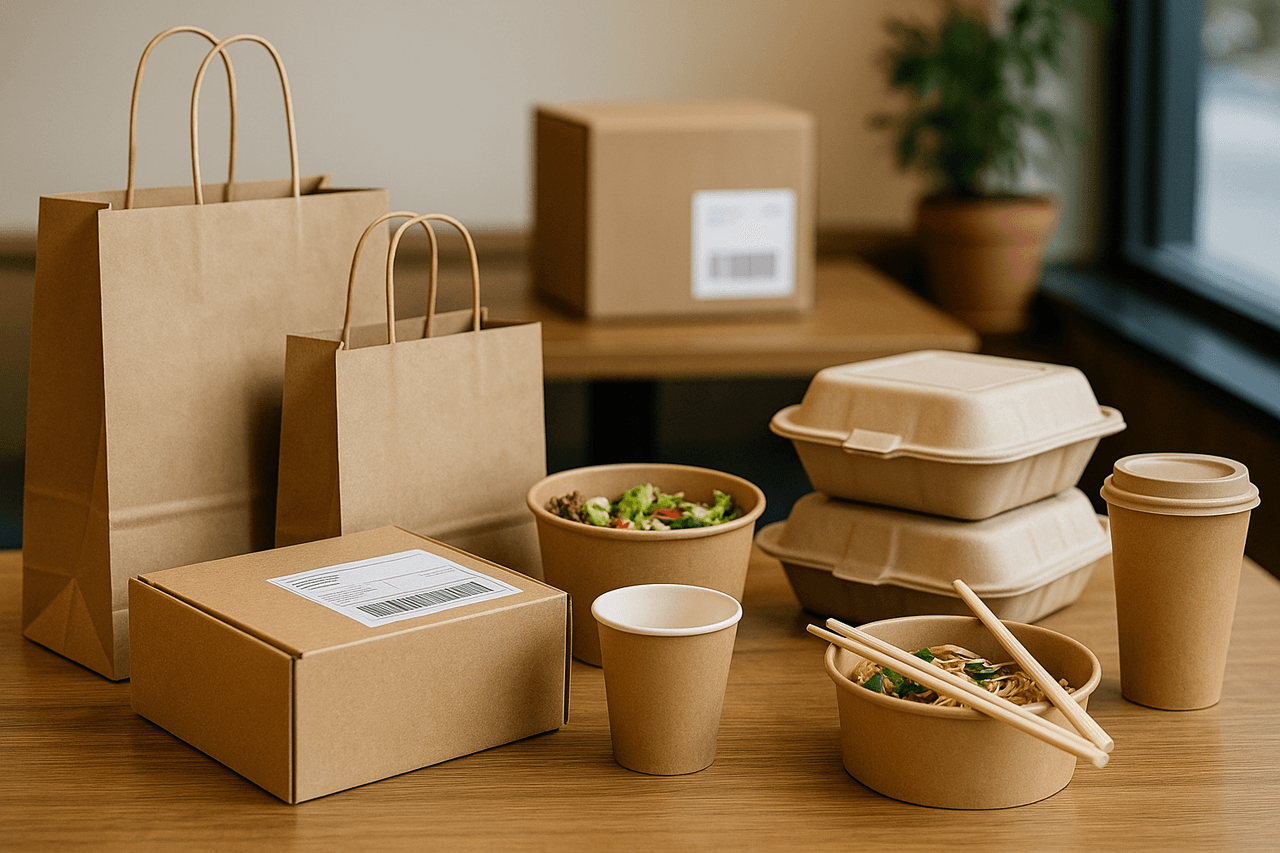
Express logistics must adopt recyclable/biodegradable mailers, fillers, and tapes.
Catering and takeaway must reduce single-use, non-degradable serviceware and adopt certified substitutes.
Brands are expected to label, trace, and document material choices and end-of-life pathways to support EPR.
For export-oriented manufacturers, 2025 is also when EU PPWR-style demands and U.S. state bans begin to shape specs. That makes a China + EU/US dual-compliance strategy essential.
2) Scope & Definitions
Recyclable: Materials that enter established collection and reprocessing streams without complex disassembly. In practice: mono-material paper or plastic, properly labeled; avoid hard-to-separate laminates.
Biodegradable/Compostable: Degradation into natural elements under specified conditions. Export buyers often require EN13432 or ASTM D6400 for compostables; domestic buyers look for China’s applicable standards and certifications.
Over-Packaging: Excess layers, void space and decorative components beyond functional needs—especially in cosmetics, gift foods, and e-commerce.
EPR (Extended Producer Responsibility): Producers/platforms take responsibility for post-consumer packaging through collection, recycling, and reporting.
Practical tip: When in doubt—simplify the structure (mono-material) and declare the end-of-life route (recycling code, compostability mark with standard number).

3) What the National Rules Aim to Achieve
Note: Regulations evolve. Treat the items below as policy themes that guide your design and sourcing. Always confirm current local requirements before launch.
3.1 Materials direction of travel
Discourage: multi-layer, non-recyclable laminates; hard-to-separate paper-plastic-aluminum composites; oxo-degradable additives; unnecessary plastic components.
Encourage / Require: recyclable mono-material solutions and biodegradable/compostable substitutes where appropriate (e.g., molded fiber/bagasse, paper, PLA/CPLA, certified coatings).
Labeling & disclosure: Clear material identification, recycling marks, and, where applicable, compostability standard references.
3.2 Over-packaging controls
Limits on layers, void ratios, and decorative elements (notably in mooncakes, health foods, cosmetics, gift sets).
Retail/e-commerce sellers expected to avoid redundant inner boxes, trays, wraps.
3.3 E-commerce & express logistics
Postal and express hubs to phase out non-degradable mailers, woven bags, and tapes; adopt recyclable/biodegradable mailers, paper fillers, and paper-based or water-activated tapes.
Encourage reusable logistics assets (totes, crates) for intra-city routes.
3.4 Foodservice & takeaway
Reduce non-degradable single-use bags, cutlery, straws, and clamshells; adopt paper/bagasse/PLA lines with food-contact tests.
Promote “upon request” provision of cutlery to trim usage.
3.5 Reporting & traceability
More pilots for digital EPR: QR codes, SKU-level material disclosures, recycled content and downstream recovery reporting.
4) Sector-Specific Impacts (What changes for you)
4.1 Food & Beverage (takeaway, QSR, catering)
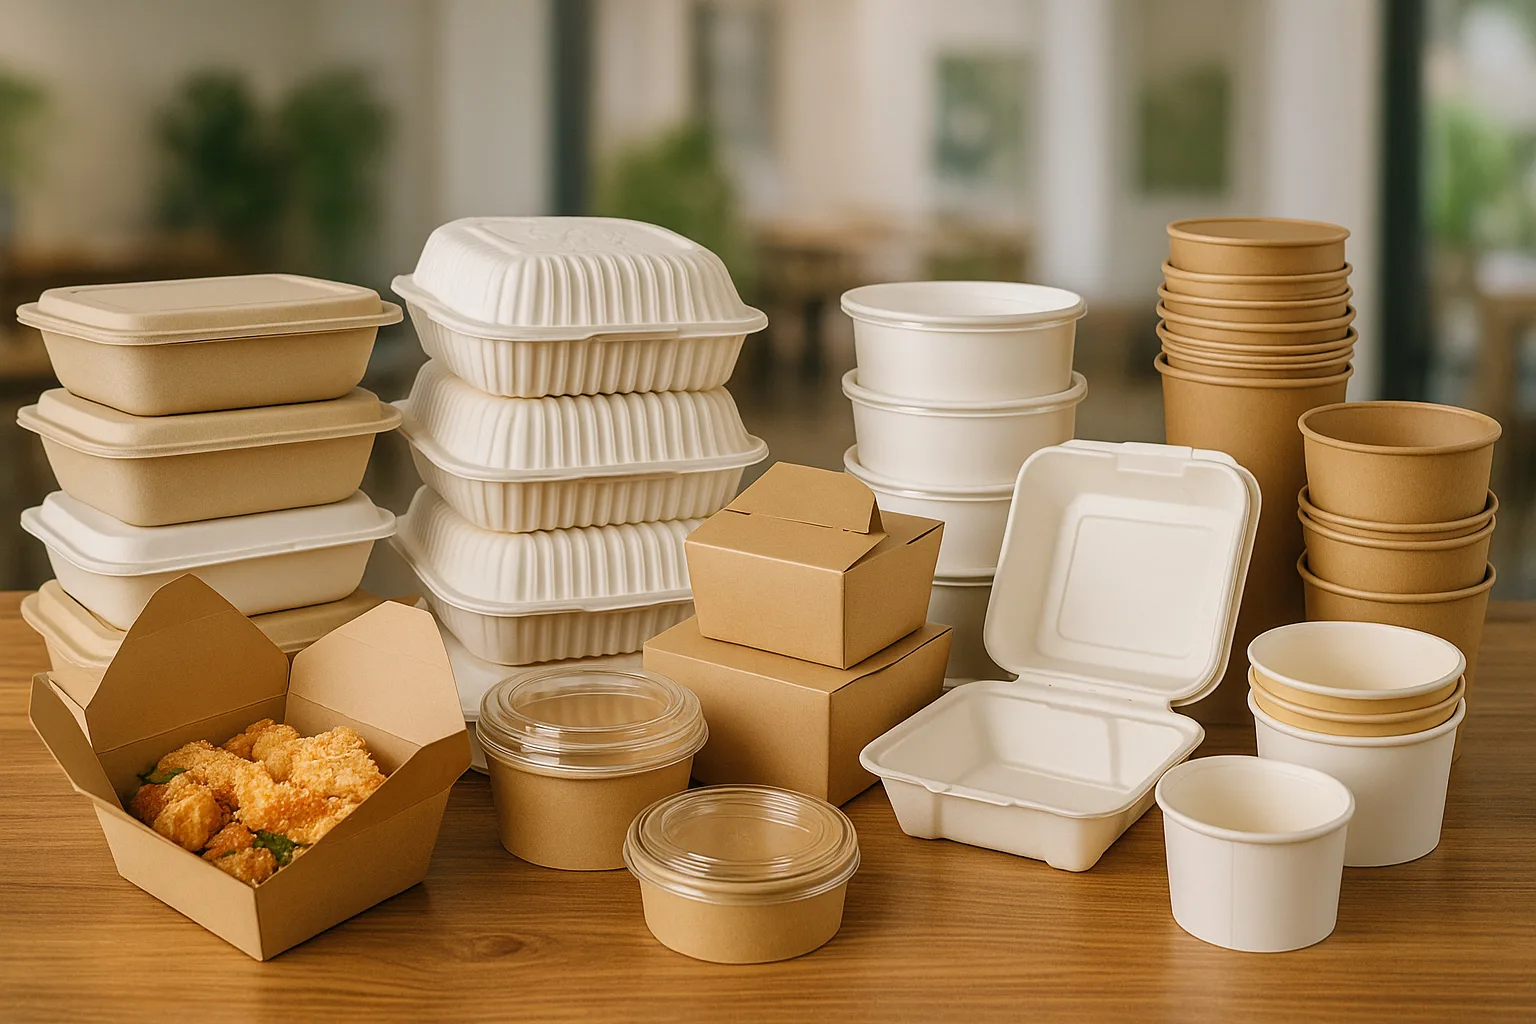
What shifts: Paper bowls, bagasse clamshells and trays, paper bags with strong handles, PLA cold cup and CPLA cutlery lines.
What to watch:
Oil/water barrier without PFAS; consider aqueous dispersion, PLA, or bio-based coatings.
Hot-fill performance and microwave stability (state limits honestly; validate with lab tests).
Avoid hard-to-recycle laminates; design for mono-material lids (PP or paper) and snap-fit without plastic films.
Quick wins: “Cutlery on request,” standardized sizes, stackable SKUs to reduce secondary packaging.
4.2 E-commerce & Logistics
What shifts: Recyclable mailers (paper), paper tape/water-activated tape, paper fillers; reusable totes in close-loop routes.
What to watch: Seal strength, drop/edge tests, weather resistance; clear recycling labeling for consumers.
Quick wins: Right-size automation, cartonization algorithms, void-fill reduction, standard mailer matrices.
4.3 FMCG & Retail (cosmetics, premium foods, gifts)
What shifts: Fewer layers, no decorative plastics, smaller void space, paperization of trays and wraps, molded pulp inserts.
What to watch: Shelf appeal with minimalist design, anti-tamper seals that remain mono-material.
Quick wins: Convert PET blisters to paperboard + window only when the window is removable; otherwise use fully paper designs.
4.4 Export-Oriented Manufacturing
What shifts: Dual-compliance specs (China + EU/US), documentation for EN13432/ASTM D6400, food-contact (FDA/LFGB), and recycled content claims.
What to watch: Importer EPR in the destination market, PFAS policies in the EU/US.
Quick wins: Offer option sets by market—e.g., PFAS-free aqueous coatings for EU, BPI/TÜV-recognized compostables for North America/EU.
5) Materials Mapping: What’s “in” for 2025
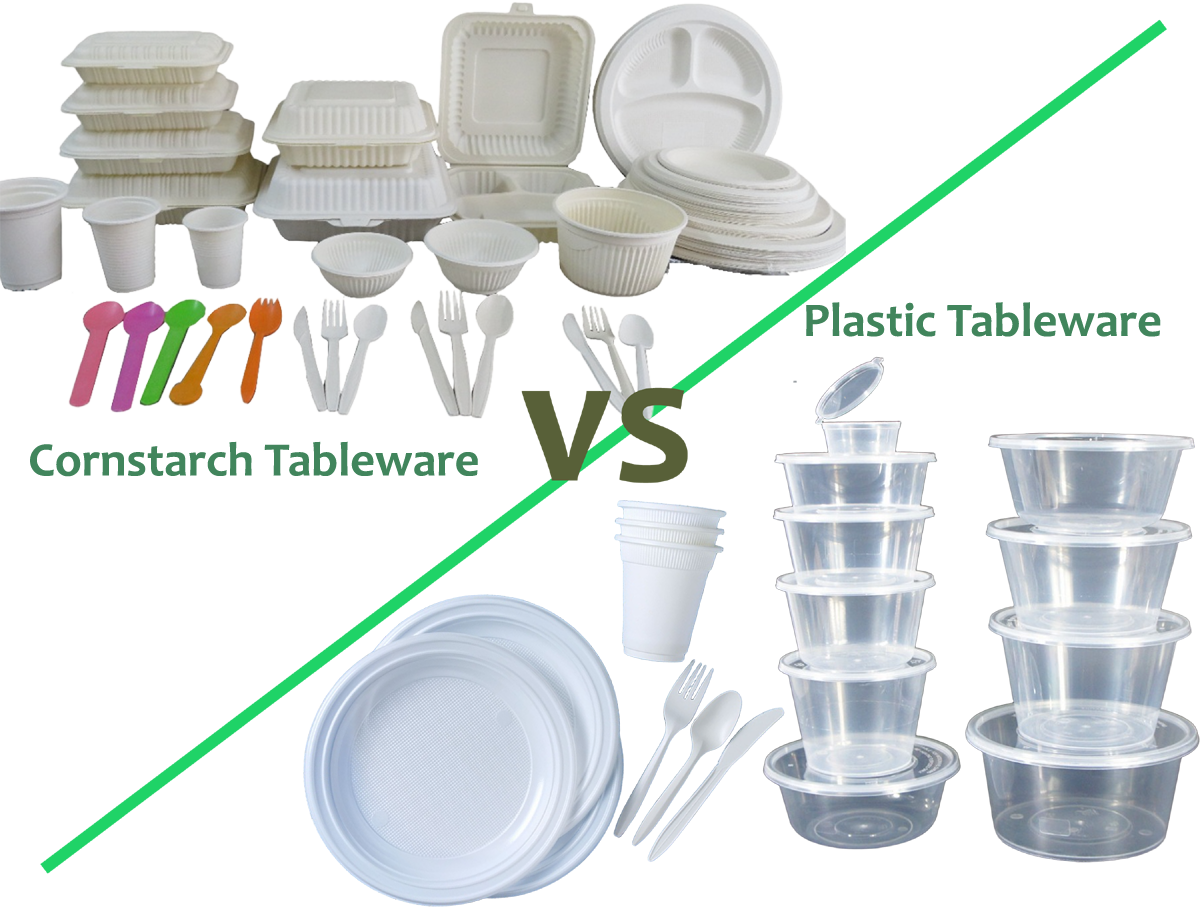
Molded fiber / Bagasse: Strong rigidity, heat tolerance, compostable; ideal for bowls, clamshells, trays.
Kraft paper systems: Salad bowls with clear lids (PET/PP), soup containers, paper carriers. Use mono-material paper lids when possible.
PLA / CPLA: Cold cups, cutlery, and coatings; ensure compostability standard references on label; confirm end-of-life options in target markets.
Barrier papers: Aqueous dispersion, bio-based coatings, or thin mono-PE where the stream accepts it; avoid mixed laminates where possible.
Design to disassemble: If you must combine, make layers visibly separable so consumers (and MRFs) can act.
6) Regional Policies & Local Outcomes in China
National rules set the framework, but local governments determine speed and texture. Three illustrative clusters:
6.1 Hainan Province — Full-scope plastic ban pioneer
Policy direction: Ambition to ban production, sale, and use of certain single-use, non-degradable plastics and promote certified alternatives.
Execution: Early prohibitions on non-degradable bags and tableware, standards for substitutes, and pilots for express packaging transformation.
Outcomes observed: Public reporting highlights high adoption of reusable/biodegradable delivery bags and formation of local compliant-materials industry clusters.
Takeaway: Hainan’s free-trade-port context and ecological goals make it a lighthouse for the rest of China—use its catalogs and pilots as a reference playbook.
6.2 Shanghai — EPR pilots + packaging reduction
Policy traits: Strong EPR (Extended Producer Responsibility) pilots, city-level rules to cut redundant packaging in retail/e-commerce.
Outcomes: Reported ~20% reductions in packaging waste in pilot zones where EPR + operational controls were tightly implemented.
Challenges: Uneven effects across districts; end-of-line collection remains the bottleneck.
6.3 Beijing / Shanghai / Guangdong “first movers” in express & retail
Focus: Stricter limits on non-degradable mailers, tapes, woven bags; push for paper mailers, paper tapes, recyclable fillers; restaurant chains to reduce plastic serviceware.
City/Province pattern: Stronger supervision and higher public awareness in megacities yield faster adoption, while townships and peri-urban areas require more support, training, and supply-side incentives.
Snapshot comparison (use in your slide to brief leadership)
| Region | Policy focus | Execution tools | Observable outcomes | Gaps to watch |
|---|---|---|---|---|
| Hainan | Broad bans; certified substitutes | Ban lists + substitute standards | High adoption in logistics & F&B | Costs; supplier qualification pace |
| Shanghai | EPR pilots; over-packaging reduction | Producer responsibility + targeted audits | ~20% waste reduction in pilots | End-of-line collection coverage |
| Beijing/Guangdong (cluster) | Express & retail restrictions | Bans on non-degradable mailers/tapes | Platform compliance acceleration | Small-outlet enforcement |
National-level direction for 2025: reduce non-degradable single-use items in foodservice; upgrade express packaging to recyclable/biodegradable; curb over-packaging across retail categories; expand EPR pilots and data reporting.
Implementation tip: Design province-aware BOMs. Where Hainan or Shanghai requires faster substitution, publish an alternate spec pack (paper/bagasse/PLA lines with certified coatings) your teams can order instantly.
7) The Compliance Playbook (Brand-ready)
Step 1 — Portfolio audit (30–45 days)
Inventory SKUs by package type, material, laminate, and end-of-life claim.
Flag risk: non-recyclable composites, oxo-degradable additives, PFAS-dependent barriers, unlabeled plastics.
Baseline KPIs: packaging weight/SKU, layers/SKU, recyclability rate, % compostable, % paperization.
Step 2 — Redesign & material decisions (45–90 days)
Prioritize mono-material designs.
Convert trays and inserts to molded fiber; deploy aqueous or PLA coatings for oil/water resistance.
For cold drinks and desserts, add PLA cup sets.
Issue Do-Not-Use lists (e.g., PET+Alu+Paper laminates, oxo-degradables).
Step 3 — Qualification & testing (concurrent, 60–90 days)
Food contact: FDA/LFGB; migration tests for coatings and inks.
Compostability: EN13432/ASTM D6400 (for export lines); domestic equivalents as applicable.
Logistics: drop, compression, burst, hot-fill/microwave (when claimed).
Labeling: recycling codes, compostability marks with standard numbers.
Step 4 — Supplier enablement & contracting (30–60 days)
Select certified manufacturers (BPI/TÜV, LFGB/FDA, ISO 9001/14001).
Set MOQ, lead times, buffer stock for provincial rollouts.
Lock PFAS-free, ink/adhesive specs in contracts.
Step 5 — EPR & data systems (Pilot in 60–90 days)
SKU-level QR or batch codes linking to material and disposal info.
Collect recycling take-back and consumer education metrics.
Report to local authorities per pilot requirements.
Step 6 — Launch & iterate (90–180 days)
Phase by province/city priority, then nationwide.
Monitor complaints, leak/warp incidents, recovery rates, and cost deltas.
Quarterly design sprints to remove residual plastics and simplify assemblies.
8) Manufacturer Opportunity Map (Build the moat)
Productization: Full families of bagasse bowls, clamshells, trays; kraft bowls with paper or PP lids; PLA/CPLA cold cups & cutlery.
Barriers: PFAS-free aqueous coatings; compostable or recyclable lid options.
Certifications: EN13432, ASTM D6400, BPI/TÜV, FDA/LFGB, ISO 22000 (food safety).
Operations: Inline QC for weight/thickness, rim dimensions, leak and stack tests; SPC to rein in scrap.
Commercial: Offer OEM/ODM, print customization, fast sample cycles, and dual-spec packs (domestic vs export).
Narrative: Position solutions as “compliance enablers” and quantify total-cost-of-ownership (less over-packaging, fewer damages, faster audits).
Bioleader® micro-case (soft insert): Export-ready bagasse bowls and kraft salad bowls with PFAS-free barrier options and PLA cup lines, validated to FDA/LFGB and compostability standards for EU/US buyers (link: Bioleader bagasse food container category; link: Bioleader paper salad bowl category; link: Bioleader compostable PLA cups category).
9) Risk Controls & Common Pitfalls
Greenwashing: Avoid unqualified “eco” labels. Tie every claim to a standard number or test report.
Composite traps: Paper-plastic-aluminum stacks are recycling dead-ends; if necessary, design for disassembly.
Barrier myths: State clearly when items are not microwaveable/hot-fillable; overselling leads to liability.
PFAS legacy: Many buyers in EU/US scrutinize PFAS. Lock PFAS-free in specs and proofs.
Supply risk: Second-source critical lines (e.g., 16/24/32 oz bowls, lid systems).
Documentation gaps: Keep material data sheets, test reports, lot traceability organized—audits are data-first.
10) KPIs & Governance (Make it measurable)
% recyclable SKUs, % compostable SKUs, % paperized.
Average layers/SKU and void ratio in e-commerce packs.
Cutlery “upon-request” adoption rate and unit reduction.
Recovery metrics: take-back participation, weight collected.
Compliance audits passed and labeling accuracy rate.
Complaint rates (leak/warp/fit), damage rate in transit.
COGS delta vs 2024 baselines and TCO savings from standardization.
11) 12-Month Roadmap (Gantt-style milestones)
Month 0–1: Portfolio audit; ban-list; KPI baseline.
Month 2–3: Redesign priority SKUs; pick suppliers; start lab tests.
Month 4–5: Pilot in Shanghai/Hainan-like high-enforcement markets; start EPR data capture.
Month 6–8: Scale to provincial clusters; switch logistics consumables (mailers, tapes, fillers).
Month 9–12: Nationwide rollout; supplier second-sourcing; quarterly design sprint; publish ESG annex on packaging.
12) Case Studies (Signals from the field)
Major platform pilots: Express hubs migrating to paper mailers and water-activated paper tapes, with void-fill reduction algorithms cutting corrugated consumption.
Food delivery chains: Transition to bagasse clamshells and paper bowls with compostable lids; cutlery provided on request to reduce units by double digits.
Bioleader®: Enabled EU/US export lines for foodservice clients by combining bagasse bowls (PFAS-free) with PLA cups and paper carriers, plus FDA/LFGB + compostability documentation for buyer audits (link: Bioleader sugarcane bagasse tableware category).
13) Future Outlook (2025–2030)
Expect a dual trajectory:
Rapid paperization and molded fiber adoption across foodservice and e-commerce.
Plastics reinvented via mono-materials and bio-based compostables in niche, high-barrier use cases.
Scale-up of digital EPR, QR-backed product passports, and AI-assisted right-sizing in fulfillment.
By 2030, leaders will treat packaging as a regulated product system—designed for recovery, tracked by data, and audited like finance.
FAQs
1) Which packaging materials are most likely to pass compliance checks in 2025?
Paper, molded fiber/bagasse, mono-material paper systems, and properly labeled compostables (PLA/CPLA) perform strongly—provided you document food contact and end-of-life (e.g., EN13432/ASTM D6400 for export).
2) Are PLA cups acceptable nationwide in China?
PLA is widely recognized as a compostable material; acceptability depends on local end-of-life pathways and labeling. For exports, reference EN13432/ASTM D6400 and buyer requirements.
3) What’s the fastest way to reduce risk for a takeaway brand?
Start with paper/bagasse containers and “cutlery on request.” Standardize sizes, swap to paper mailers/tapes for delivery, and ensure PFAS-free barrier options with verified tests.
4) How should we handle lids—paper, PP, or PLA?
Use mono-material where possible. Paper lids for ambient foods; PP lids for recyclability in many streams; PLA for compostable sets. Avoid PET-laminated paper unless you can separate layers.
5) What documentation will auditors ask for?
Material safety (FDA/LFGB), compostability (EN13432/ASTM D6400 as applicable), migration tests, barrier specs, and labeling conformance. Keep SKU-level BOMs and lot traceability.
6) Does EPR apply to importers/exporters?
EPR responsibilities differ by jurisdiction. In China, pilots increasingly involve platforms and producers; in the EU/US, importers often shoulder EPR. Plan for dual reporting.
7) How do we quantify success?
Track % recyclable/compostable SKUs, weight per order, cutlery reduction, complaints vs leakage/warp, collection rates, and audit pass rates. Tie gains to ESG reporting.
References
Smithers (2023). The Future of Paper vs Plastic Packaging to 2030
McKinsey & Company (2025). Do US consumers care about sustainable packaging in 2025?
European Commission (2024). Packaging and Packaging Waste Regulation (PPWR)
Two Sides (2025). Trend Tracker 2025: Consumer Preferences for Packaging
Ellen MacArthur Foundation (2023). The New Plastics Economy: Catalysing Action
Statista (2024). Global Paper & Paperboard Packaging Market Value 2019–2030
UNEP (2023). Turning Off the Tap: How the world can end plastic pollution and create a circular economy
Decision Framework & Semantic Loop
How to move now: Run a 6-step sprint—Audit → Redesign (mono-material, paperization, bagasse/PLA) → Validate (food-contact/compostability/logistics) → Pilot (high-enforcement cities) → Scale (province-aware BOMs) → Govern (EPR data, KPIs, audits).
Why this works: It aligns with the 2025 enforcement cadence, reduces regulatory exposure, improves consumer trust, and can lower total cost by right-sizing and SKU standardization.
What to build: A portfolio of bagasse bowls/clamshells, kraft bowls with paper/PP lids, PLA/CPLA cold cups, PFAS-free aqueous coatings, barrier papers, reusable logistics assets, and QR-backed product passports.
Options & trade-offs: Paper/Bagasse (+ perception, + recyclability/compostability, – barrier without coatings); PLA/CPLA (+ compostable sets, – context dependent end-of-life); PP mono-material (+ recyclability in many streams, – perception); laminates (only if separable).
Considerations & KPIs: % recyclable/compostable SKUs; layers/order; leak/warp ppm; right-sizing rate; take-back weight; audit pass rate; PFAS-free conformance; documentation completeness.
Next 90 days: Publish a Do-Not-Use list; lock PFAS-free specs; convert logistics to paper mailers/tapes; standardize lids; launch pilots in two cities; set up QR and reporting templates for EPR pilots.
Independent Citations
External sources that have cited or referenced this Bioleader resource.
Solinatra
Referenced this Bioleader resource in an industry overview of packaging regulations in China.
View source